Forward Pricing
A casual walkthrough of forward pricing for zero coupon bonds — showing how today's spot rates imply a locked-in future price, and why realized rates rarely match what we expected.
Feels like I’m basically re-running the Implied forward rate stuff I already covered before… honestly I wanted to just skip this whole part lol. But it’s in the book, so — let’s (once again) take a quick peek.
At the current point $T=0$, all kinds of zero coupon rates are floating around out there in the market. And I mentioned that the forward rate you compute from those spot rates is what we call the implied forward rate.
So at $T=0$, a 2-year zero coupon bond with $1 face value is going for
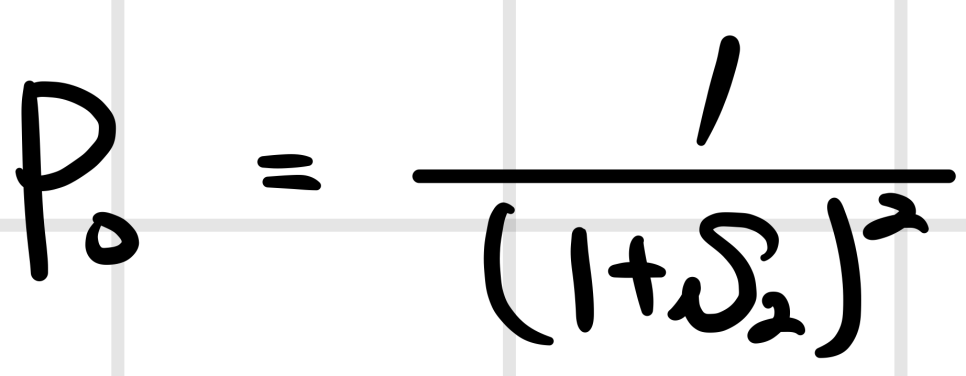
That’s the price it’s trading at, right?
Now if you promise today to sell that same bond one year from now — what price would be the rational one to lock in?
The price below is exactly that rational locked-in number — the Market Fair Value. (It’s the delivery price today’s curve implies, with no arbitrage; it’s not a forecast that the bond will actually trade at that price a year from now.)
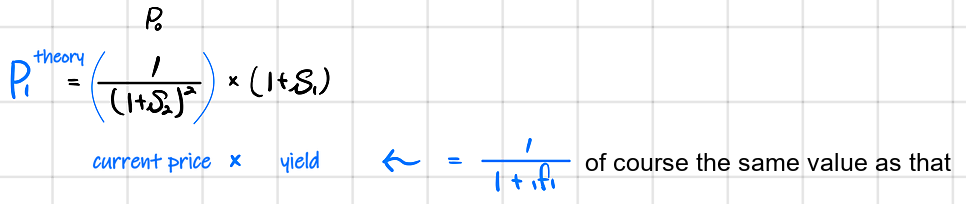
And honestly… that’s the entire Forward Pricing chapter.
But OK — when $T=1$ actually rolls around, is the 1-year yield as of $T=1$ — let’s call it $s_1'$ — going to match the $_1f_1$ we expected (computed) back in the past??
Obviously not — not exactly, anyway. Market rates don’t sit still. There’d be trades happening between people who think $s_1'$ will end up higher than the $_1f_1$ implied at $t=0$, and people betting it’ll come in lower.
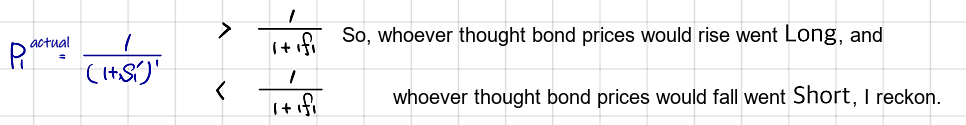
Now let’s look at the same thing but just stretch the timeline a bit:
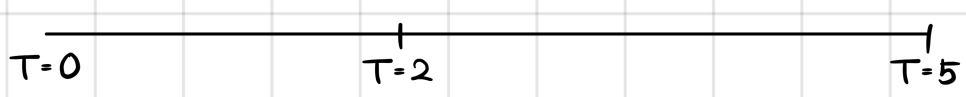
At the current point $T=0$, a zero coupon bond with a 5-year maturity
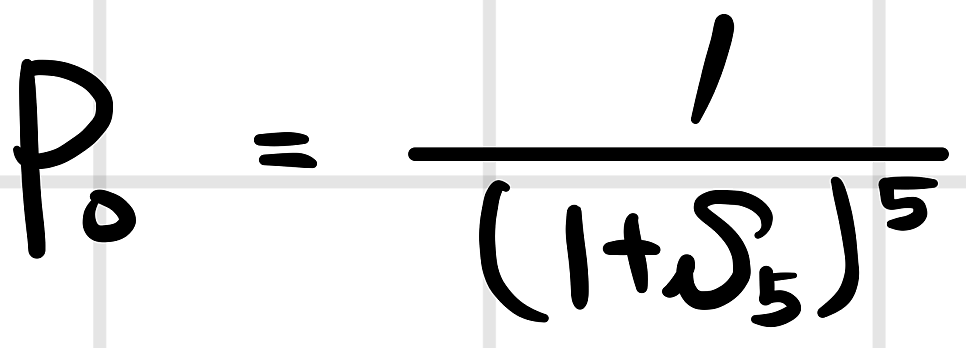
is trading at this price. If you enter a contract (forward) to buy/sell this bond at $T=2$, the Market Fair Value comes out to
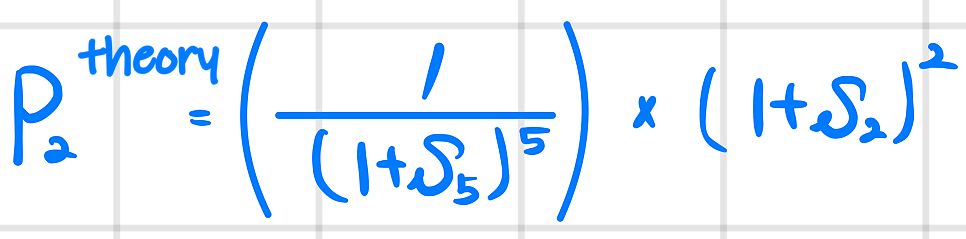
That’s literally all it’s saying bro. Forward Pricing has, like… genuinely nothing to it. T_T
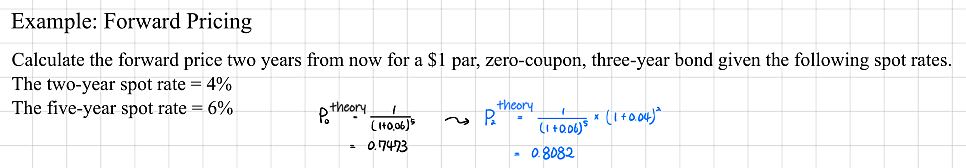
The Forward Rate Model
OK, this time — instead of the Forward Pricing we just did, we’re talking about measuring the “Rate” itself. And in the book it’s written out with this kind of formula:
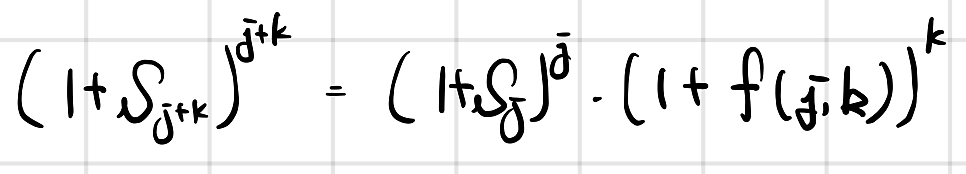
But if we just slap it on a timeline and rewrite it in our own notation,
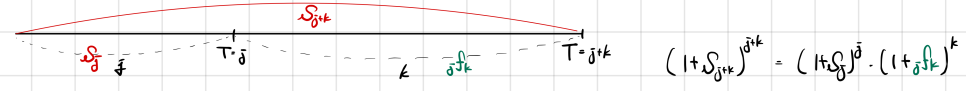
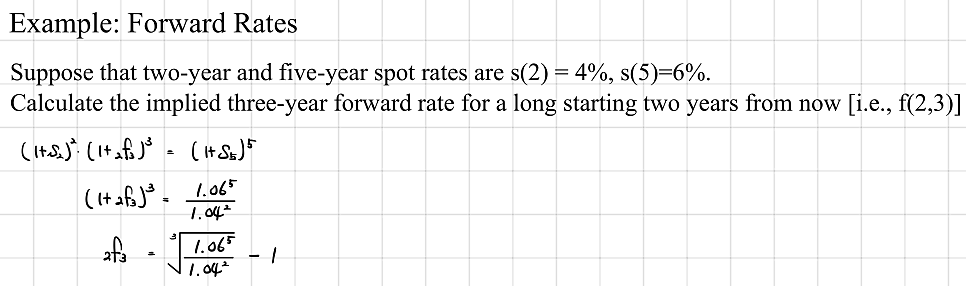
Wait — it’s literally the same thing lol! The only difference is we’re writing it in terms of yield instead of price.
Done!
Comments
Discussion happens via GitHub Discussions. You'll need a GitHub account to comment.