Midterm Exam Review
My handwritten notes for the midterm so far: put-call parity, binomial trees, the Black-Scholes assumptions and formulas, the Greeks, and the VBA code behind all of it.
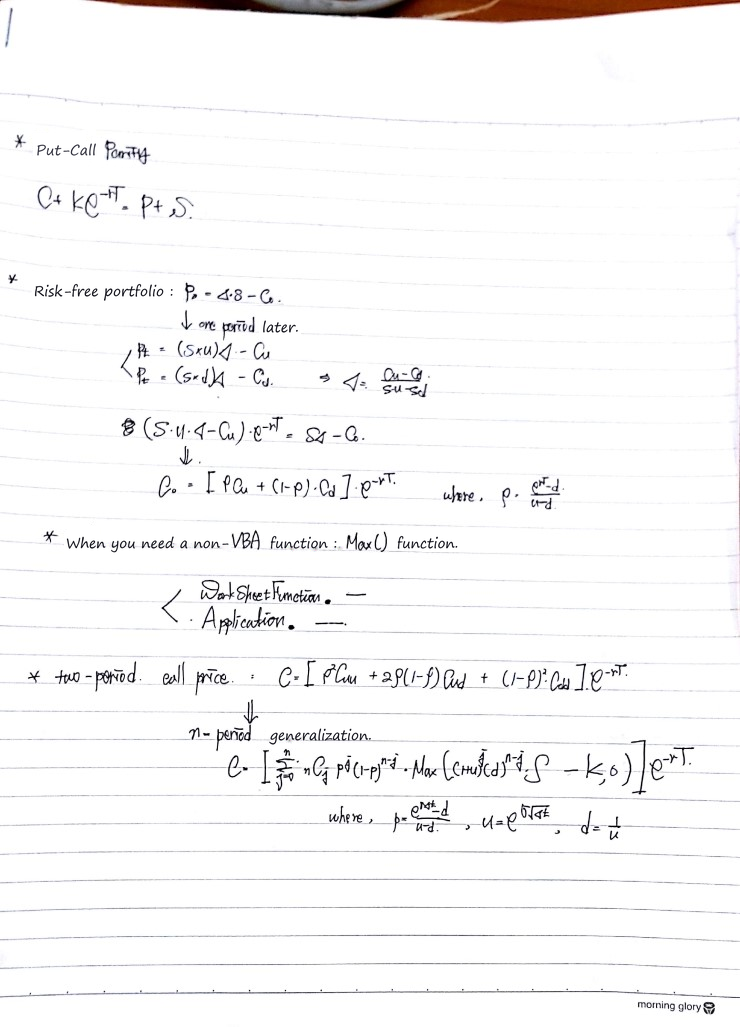
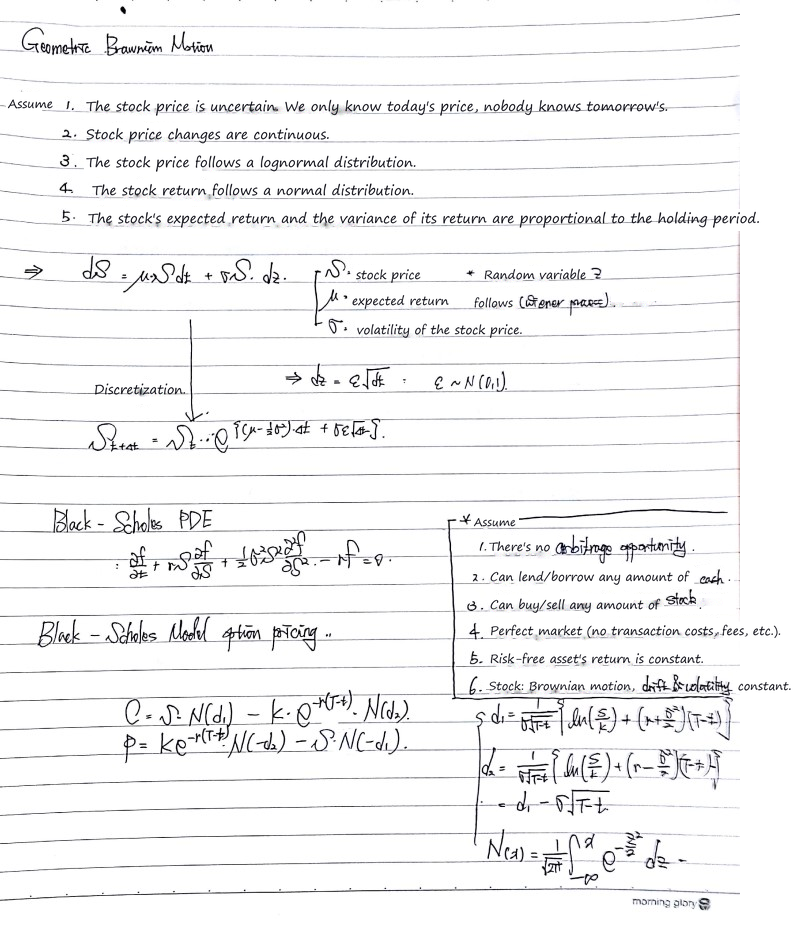
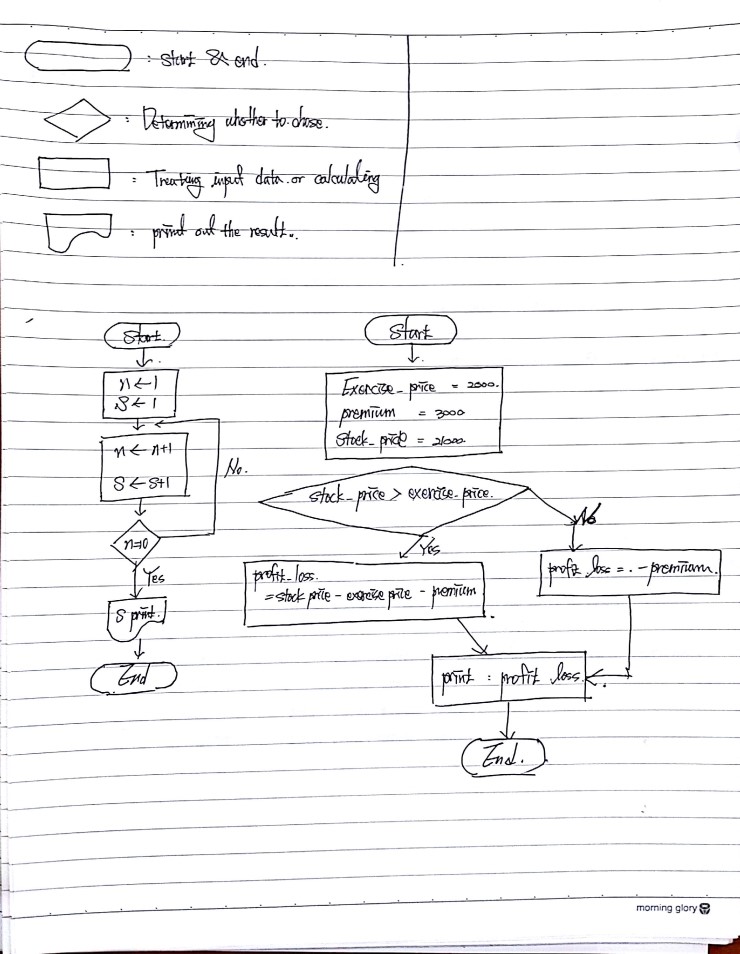
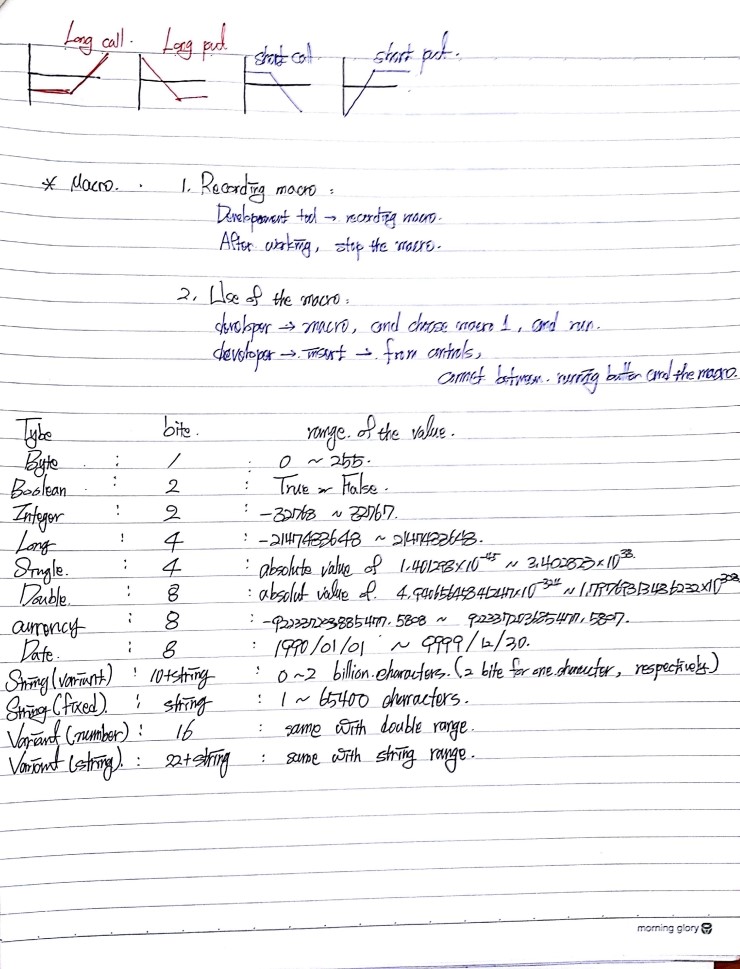
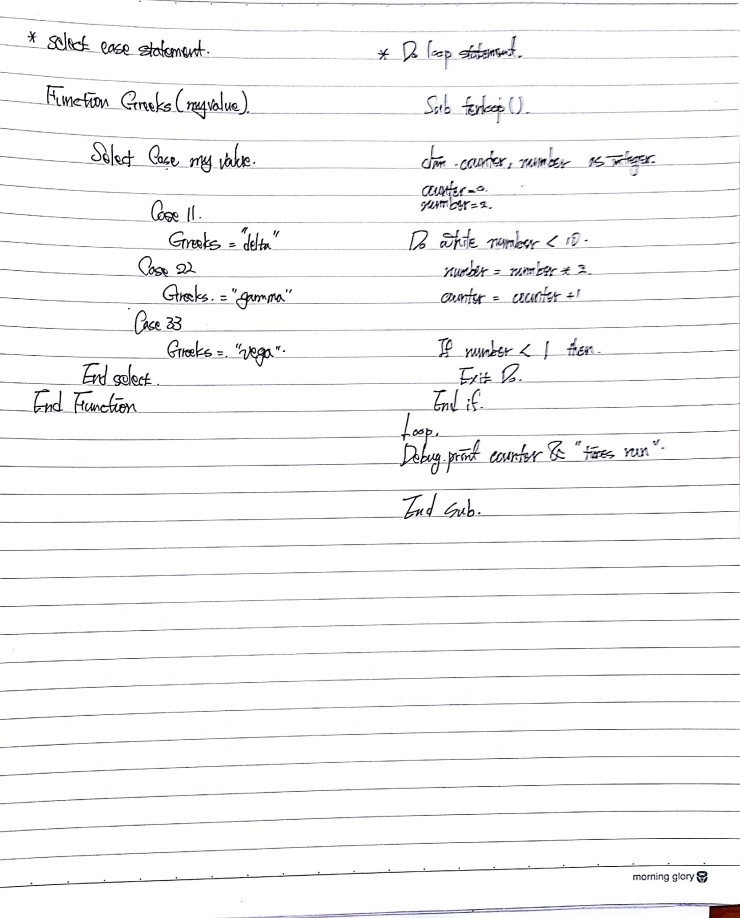
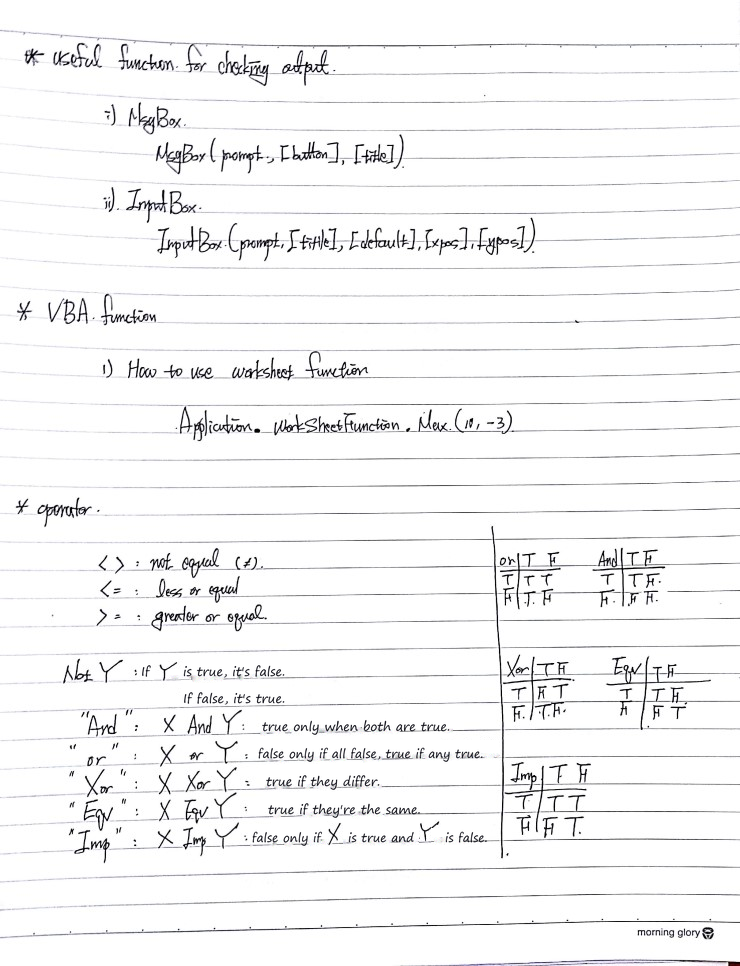
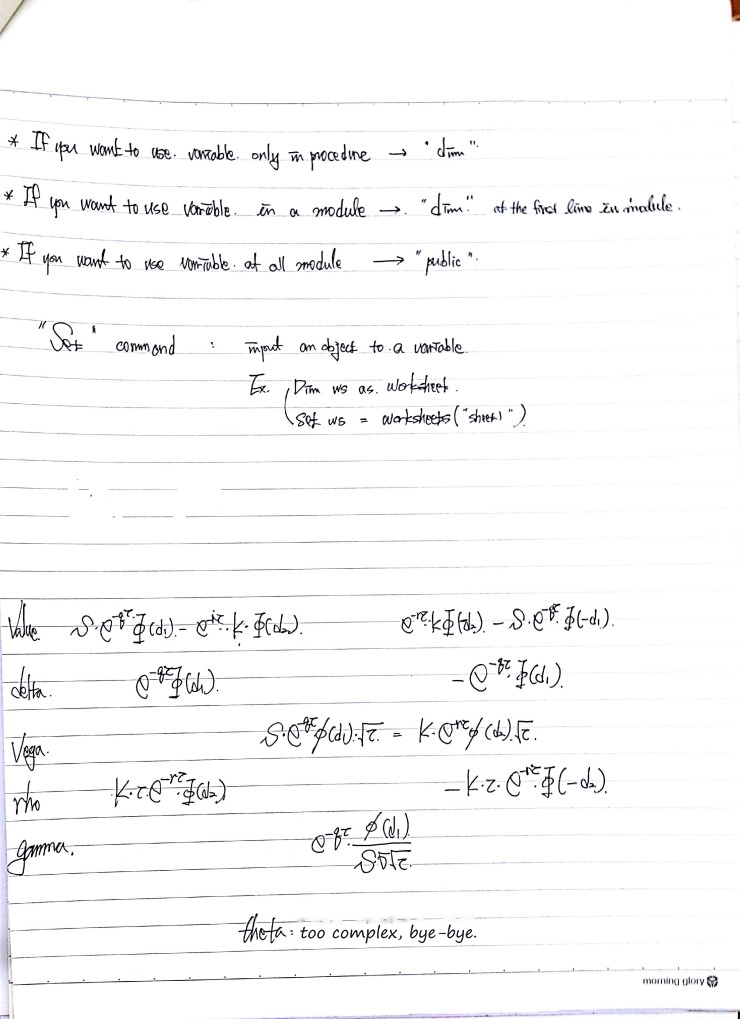
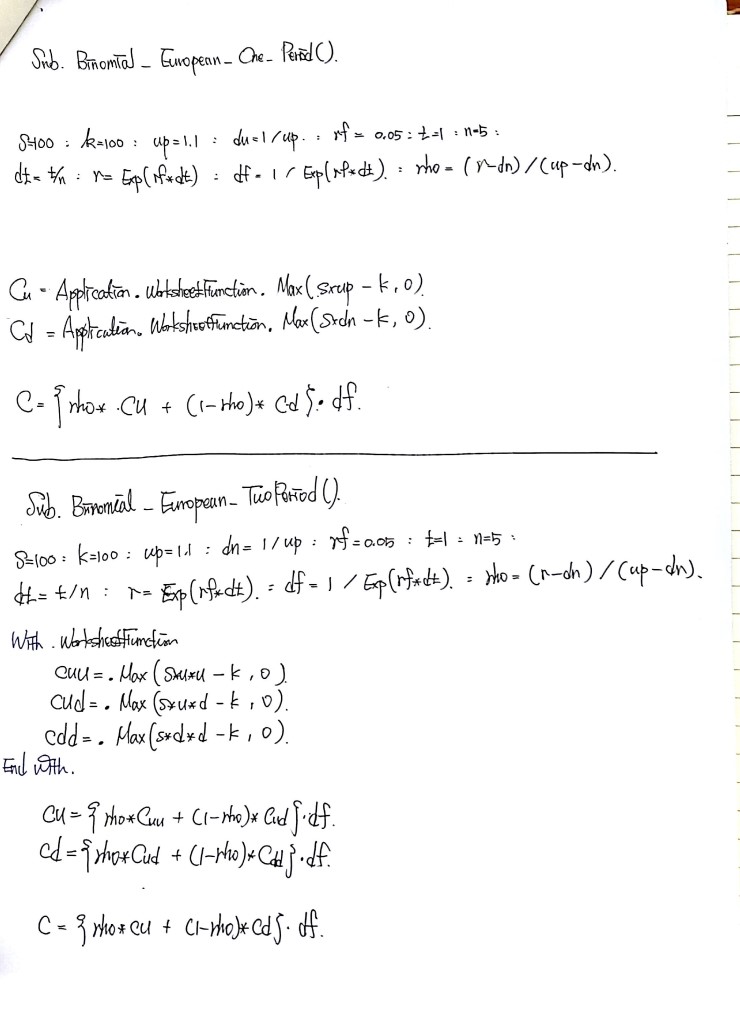
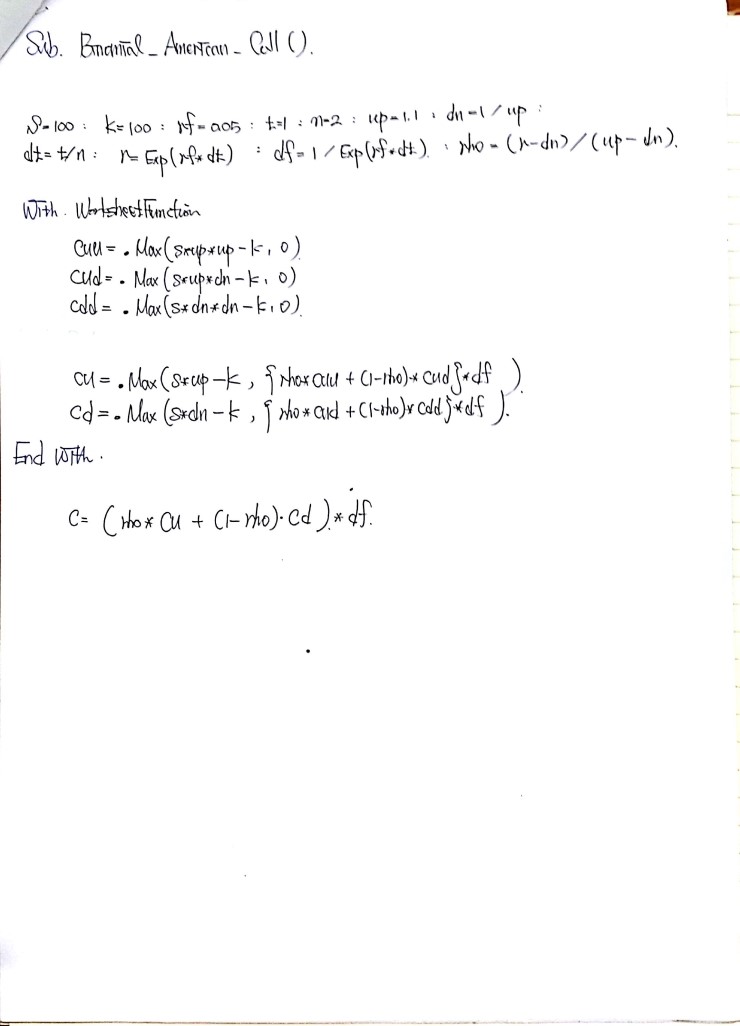
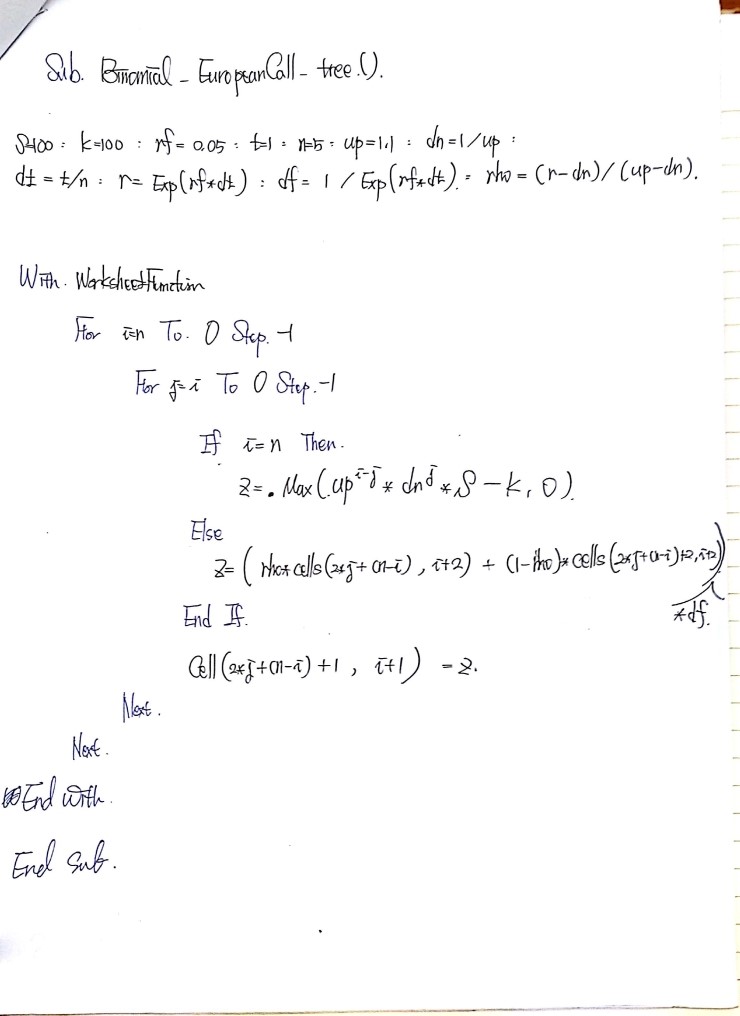
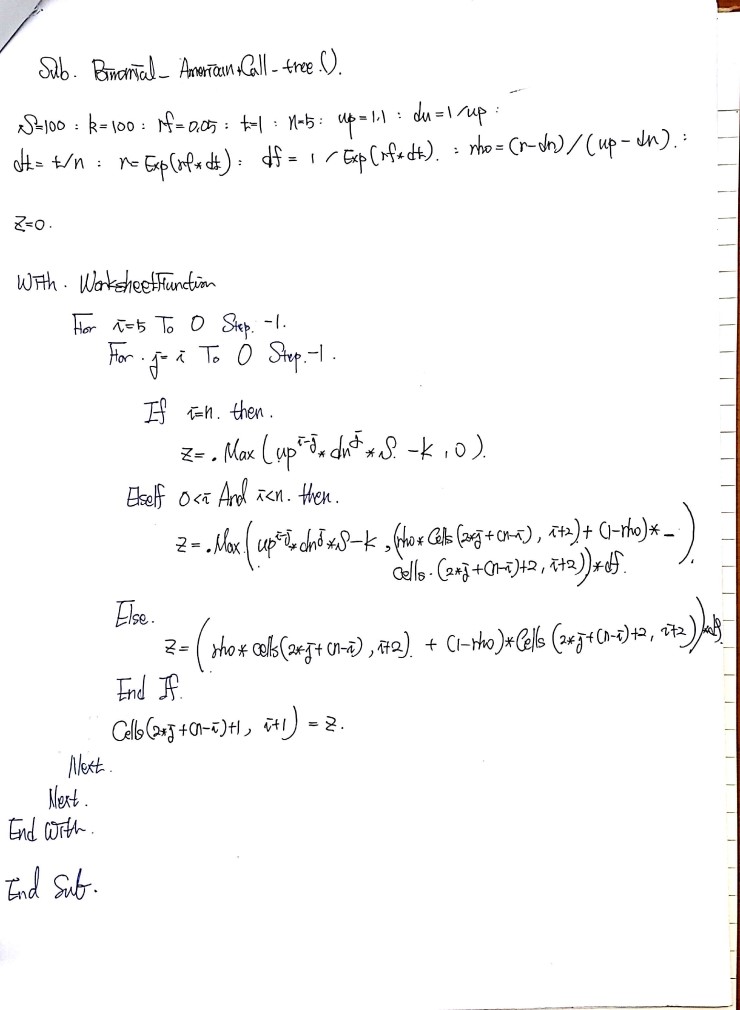
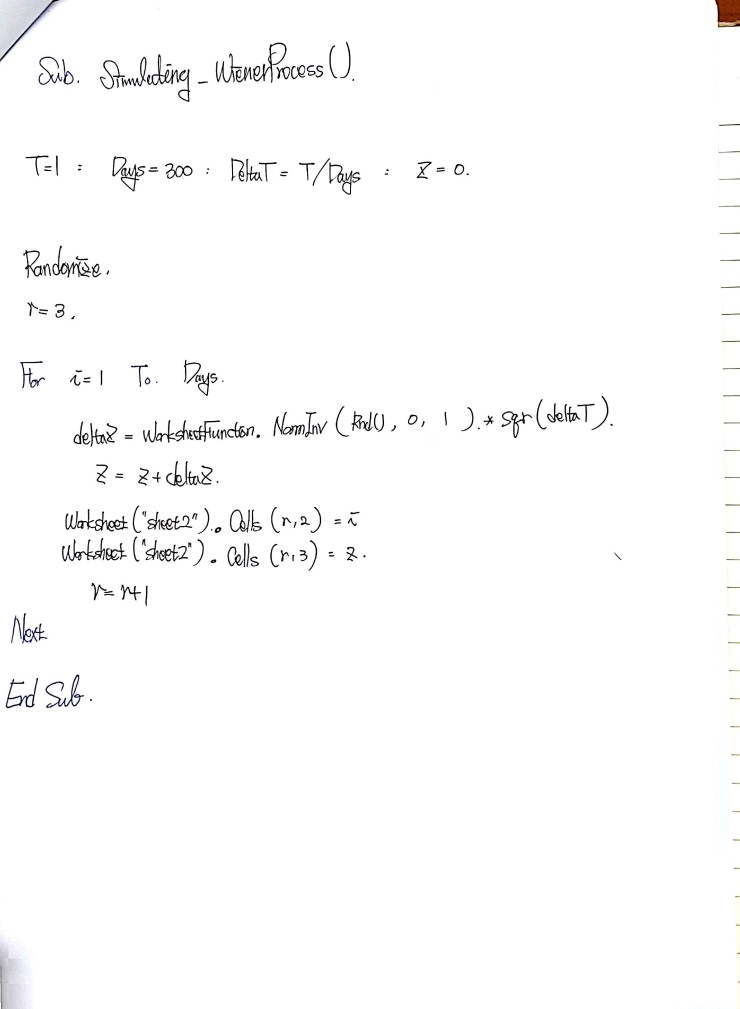
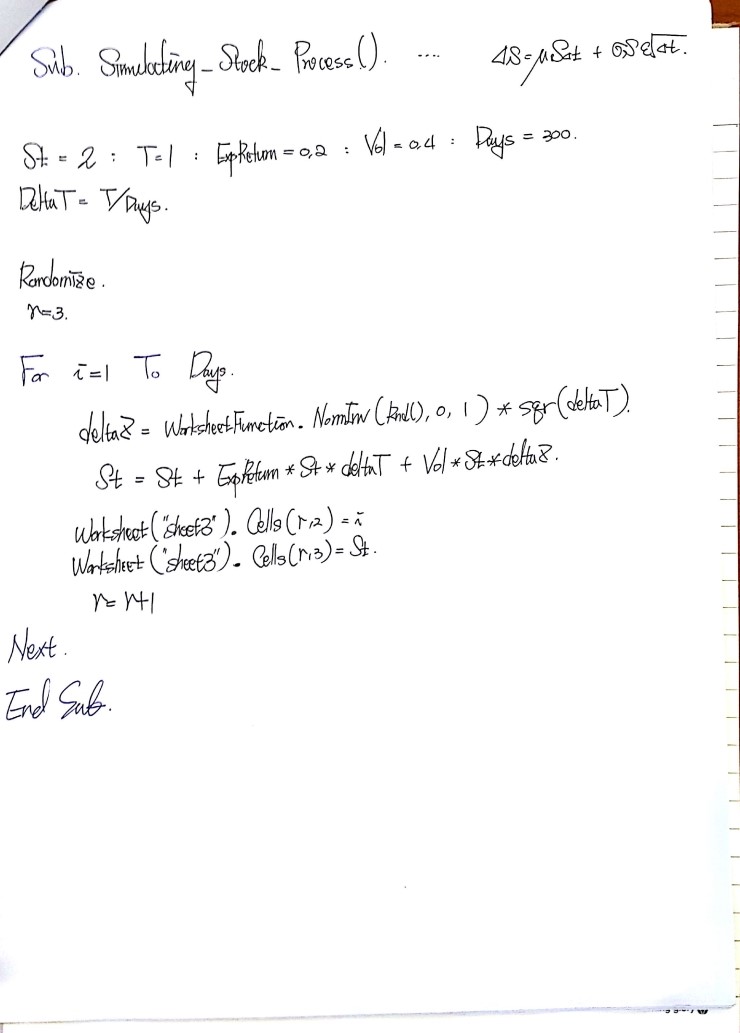
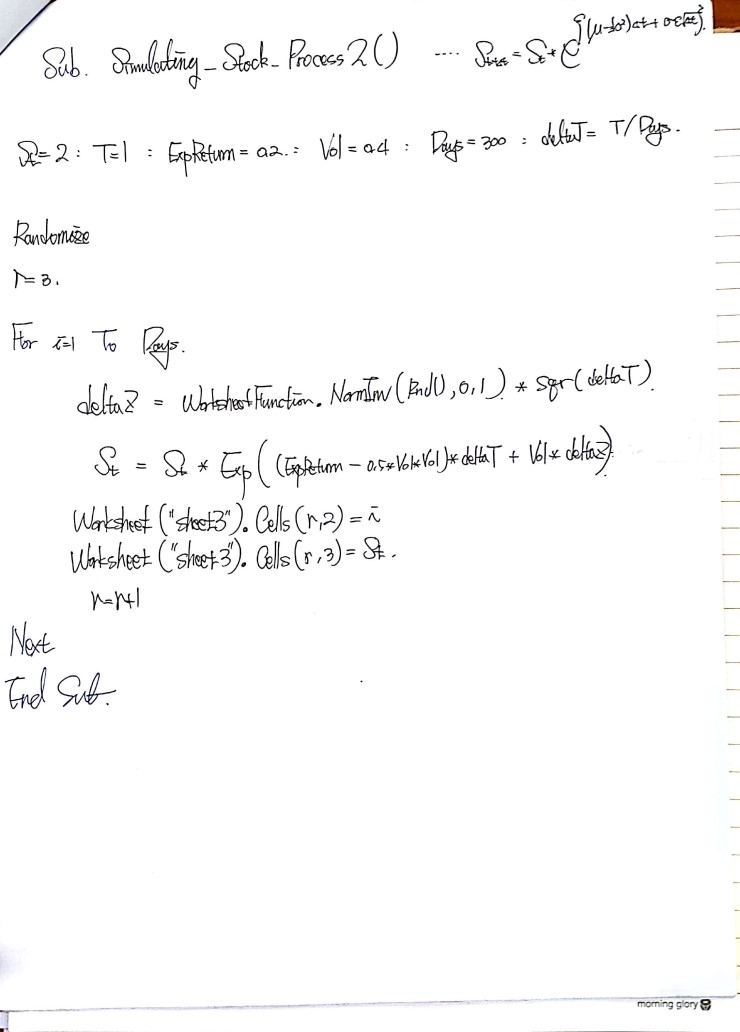
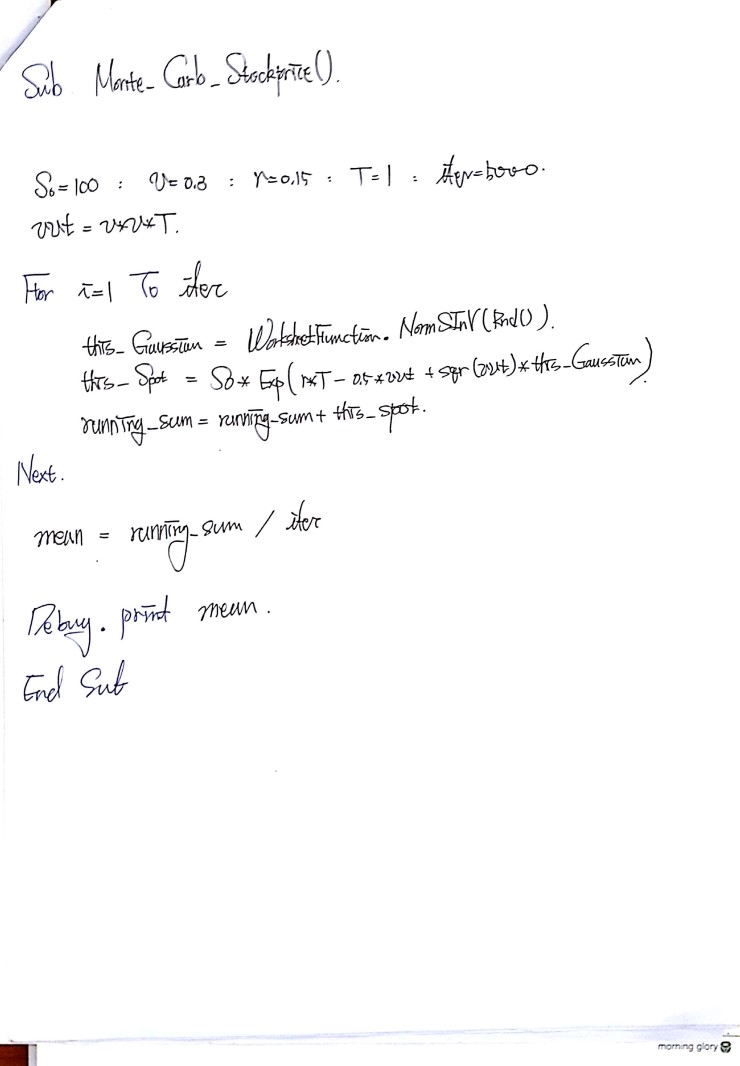
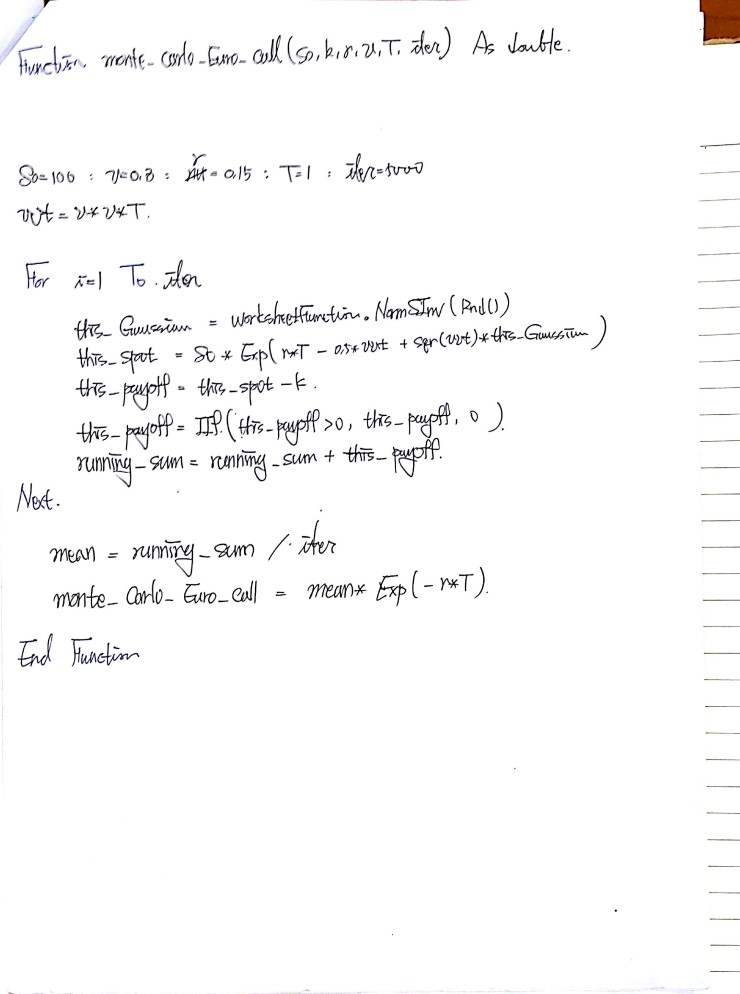
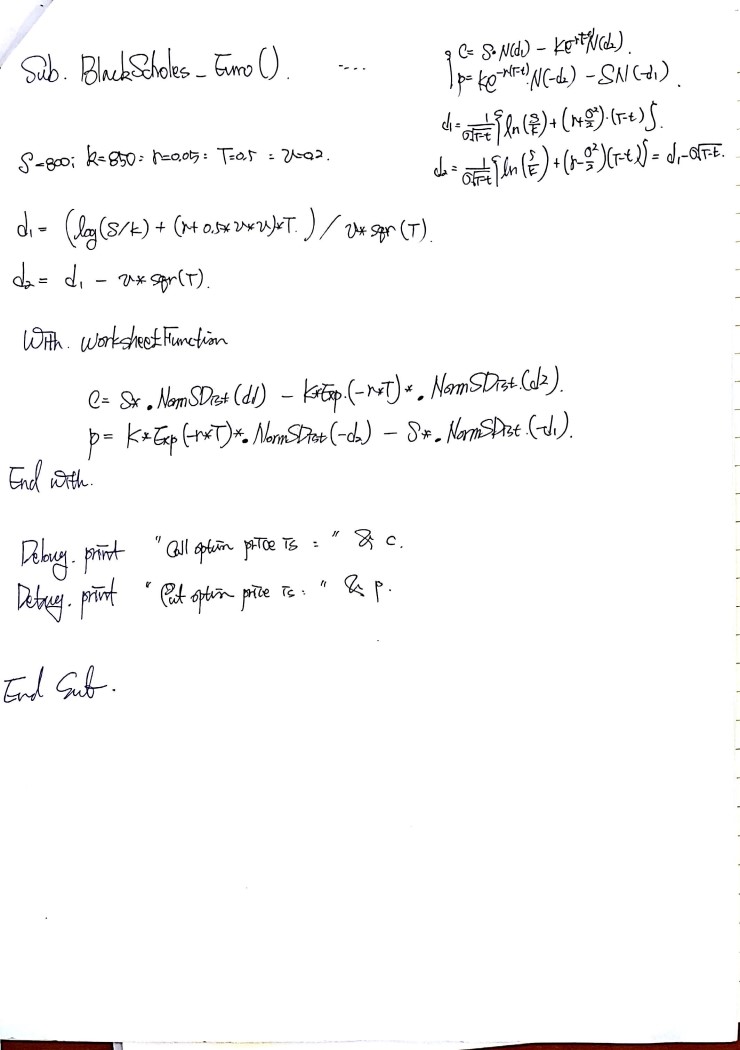
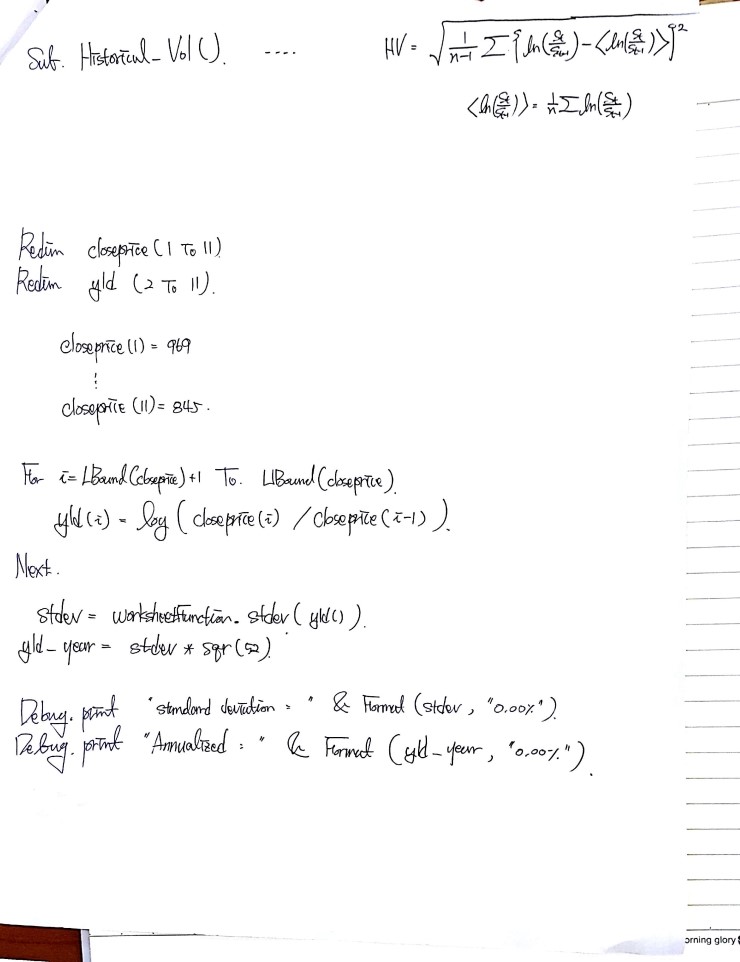
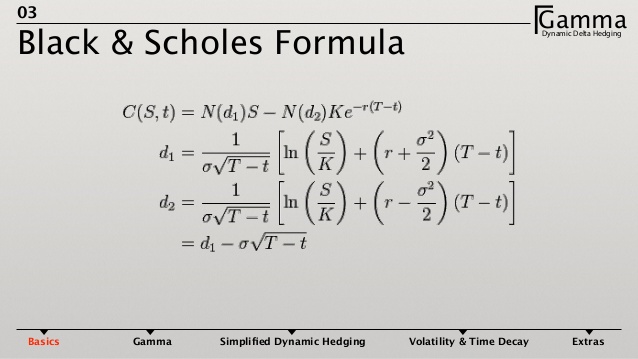
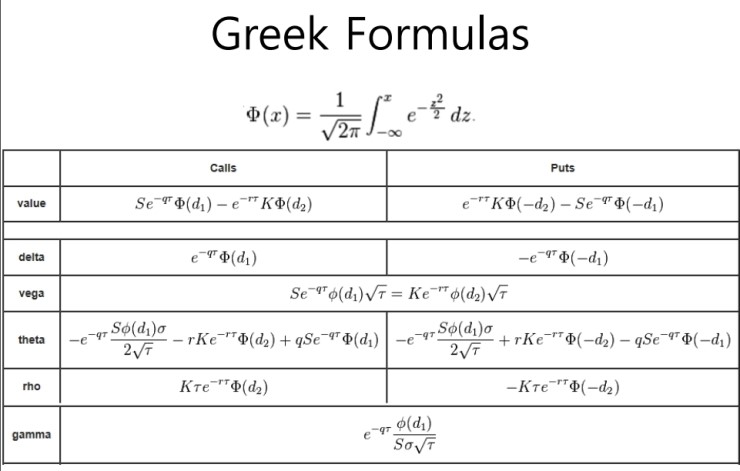
Image sources:
- anthony-vba.kefra.com/vba/vba13.htm
- Erdem Tokmakoglu — Option Gamma & Dynamic Delta Hedging (SlideShare)
Heads-up. The figures here are the original notes, slips and all. A few things to watch for:
- In the table of VBA data types, the Date range is January 1, 100 to December 31, 9999, not 1990/01/01 to 9999/12/30.
- In the operator notes, read the Imp truth table with the rows as Y and the columns as X: X Imp Y is false only when X is true and Y is false.
- In the Greeks table, the put delta is $-e^{-q\tau}\Phi(-d_1)$, not $-e^{-q\tau}\Phi(d_1)$.
- In the two binomial routines, $t = 1$ with $n = 5$ makes each step 0.2 years; for one and two periods to maturity, $n$ should be 1 and 2. The two-period routine also writes u and d where its variables are named up and dn.
- In the Black-Scholes code, the denominator of d1 needs parentheses: d1 = (Log(S / K) + (r + 0.5 * v * v) * T) / (v * Sqr(T)). Written as / v * Sqr(T), VBA divides by v and then multiplies by Sqr(T), so d1 comes out multiplied by T and the call price is off (32.67 instead of about 32.86).
Comments
Discussion happens via GitHub Discussions. You'll need a GitHub account to comment.